By Eng. Juan Alexis Cedeño Castillo, civil engineer and certified appraiser at Tasaciones Valor Seguro.
If you are buying, building or refinancing a property with a loan in the Dominican Republic, the bank will ask for an appraisal. It is the technical report that establishes what the property is worth, and that value determines how much the bank will lend you.
In this guide we explain, from the experience of an appraiser who works daily with banks and credit unions in La Altagracia and La Romana provinces, what you need, how long it takes and how to avoid surprises.
What is a bank appraisal?
A bank appraisal is a report prepared by a certified appraiser approved by the lender. It determines the market value of a property so it can be used as collateral for a loan. The bank uses that value, not the price you agreed with the seller, to calculate the maximum amount it can finance.
What documents do I need for a property appraisal?
To request an appraisal you need:
- The property’s legal document: certificate of title, promise of sale agreement or sales contract.
- ID of the person requesting the appraisal (Dominican ID card or passport).
- The purpose of the appraisal: bank loan, sale, insurance, estate, court case, etc.
- The property’s location (address or Google Maps location).
- A short description of the property: type (house, apartment, lot, commercial space, villa), number of floors, approximate size.
- A photo of the front or the site, so we can gauge the work involved and send you a quote.
If the appraisal is for a bank, we also need:
- The name of the lender (Banreservas, Banco Popular, BHD, Ademi, a credit union, etc.).
- The details of the loan officer handling your loan, so we can send the report directly.
Important: the certificate of title (or the property’s legal document) must be available before the visit. Without it we cannot carry out the inspection, because we need to have it on hand during the survey.
How long does a bank appraisal take?
The report is usually delivered 2 to 3 business days after the inspection. Timing may vary depending on the type of property and its complexity: luxury villas, buildings, large plots of land or properties with incomplete documents may take longer.
The process has four steps:
- You send the documents and the property information.
- We send you a quote.
- We schedule the on-site inspection.
- We prepare the report and send it to you and to the bank.
How much does a property appraisal cost in the Dominican Republic?
There is no single price. The cost of an appraisal depends on several factors, mainly:
- The type of property: an apartment does not require the same work as a villa, a building or a large plot of land.
- The size and complexity of the property.
- The location and travel distance for the visit.
- The purpose of the appraisal: bank, court, insurance or sale.
- The minimum fees set by the Dominican Institute of Appraisers (ITADO), which certified professionals must follow.
That is why we ask for the location, description and a photo before quoting: so we can give you an exact price, not an estimate.
What happens if the appraisal comes in lower than the purchase price?
This is the most common concern, and the explanation is simple: the bank lends based on the appraised value or the purchase price, whichever is lower. Most lenders finance up to about 80% of that value.
Example: if you agreed to buy for RD$6,000,000 but the appraisal comes in at RD$5,500,000, the bank calculates the loan on RD$5,500,000. You would have to cover the RD$500,000 difference yourself, on top of the down payment.
What can you do?
- Renegotiate the price with the seller, using the appraisal as technical support.
- Increase your down payment to cover the difference.
- Check whether information was missing: improvements, finishes or areas that were not documented.
An objective appraisal protects you: it keeps you from paying more than the property is really worth.
Why won’t the bank accept just any appraiser?
Each bank works with a list of approved appraisers. If your appraisal is done by a professional who is not on that list, the bank may reject it and you would have to pay for another one. Before hiring, confirm with your loan officer that the appraiser is approved by your bank.
Eng. Juan Alexis Cedeño, of Tasaciones Valor Seguro, is an approved appraiser for Banreservas, Banco Popular, BHD, Ademi and several credit unions. Learn more about our bank and private appraisals.
Frequently asked questions
Can I use an old appraisal? Generally not. Banks ask for recent appraisals because property values change over time.
Who pays for the appraisal, the buyer or the bank? It is normally paid by the person applying for the loan.
Can a property under construction or on plans be appraised? A property that exists only on plans cannot be appraised. For a bank appraisal, the property must be 100% finished. For a villa under construction, an appraisal can be done to establish the construction progress and the amount invested.
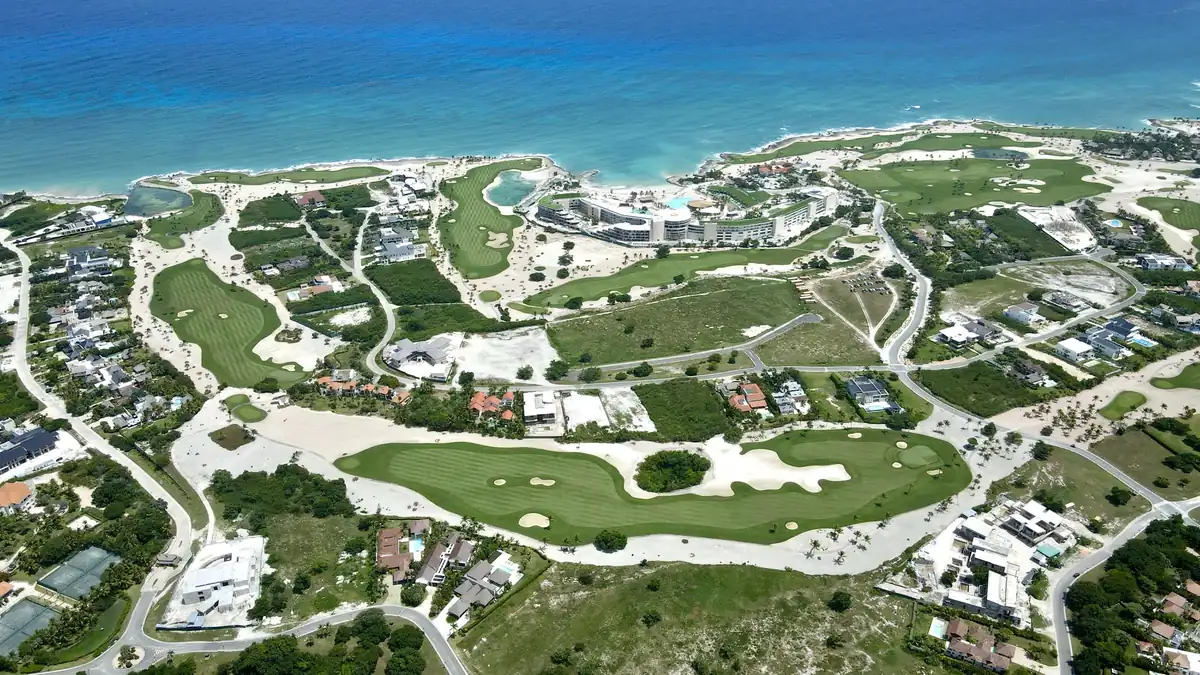
Do you provide appraisals in Punta Cana, Bávaro and Cap Cana? Yes. We work in La Altagracia and La Romana provinces, including Higüey, Punta Cana, Bávaro, Cap Cana, Bayahibe, La Romana and their resort areas.
Ready for your appraisal? Send us the location, a short description and a photo of the property on WhatsApp and we will send you a quote: Request a quote on WhatsApp
Last updated: October 2026